Broxbourne is our closest Hertfordshire neighbour. From Roydon it is just across the River Lea, and many of the people we help there are thinking about pensions: how many they have, what they are invested in and how to use them well.
Broxbourne the place, Broxbourne the borough
The name can mean two things. Broxbourne is a riverside town on the western bank of the Lea, and it also gives its name to the wider Borough of Broxbourne, which includes Cheshunt, Hoddesdon and Waltham Cross. This page is about the town and its immediate surroundings; if you are in Cheshunt or Hoddesdon, see their own pages below.
Broxbourne station is where the Hertford East branch leaves the West Anglia Main Line, so there are direct trains to London Liverpool Street. The New River runs through the area, and Broxbourne Woods lie to the west of the A10.
A closer look at pensions
Pensions are one of the areas we are asked about most, so here is a short guide to the common situations.
Too many pots
If you have pensions from several jobs, it can be hard to see the whole picture. We can review them together and consider whether consolidating makes sense. Sometimes it does, sometimes it does not: older pensions can carry valuable guarantees or charges for leaving, so we check before recommending anything.
Not sure how it is invested
Many people have never looked at the funds their pension is invested in. We can explain what you hold and whether it still suits your timescale and attitude to risk.
Separating or divorcing
A pension can be one of the largest assets in a divorce. Our guide to pensions and divorce explains how pensions can be shared or offset.
Getting ready to retire
We can help you decide when to retire, how to draw an income and how your pensions fit with the State Pension and other savings. See our pensions and retirement page.
Beyond pensions
Investments. If you have savings beyond your pension, our investments page explains how we approach investing.
Mortgages. Kealy Ball can help with buying, moving and remortgaging. If you have savings as well as a mortgage, an offset mortgage may be worth considering. Visit the mortgages page.
Protection. Life, critical illness and income cover for you and your family. See protection.
Business protection. For local business owners, our business protection page explains key person and shareholder cover.
Pension or ISA?
It is one of the questions we hear most. Both can be tax-efficient, but they work differently:
- Pensions usually receive tax relief on the way in, and the money is generally locked away until at least 55 (rising to 57 from April 2028). Part can usually be taken tax-free, with the rest taxed as income.
- ISAs do not receive tax relief on the way in, but withdrawals are tax-free and you can usually take money out at any time.
- Employer contributions can make a workplace pension particularly valuable.
For many people the answer is a mix of both: a pension for retirement, and ISAs for flexibility. The right balance depends on your income, your goals and when you are likely to need the money. Tax treatment depends on individual circumstances and may change in the future.
Meeting us
You can meet us at our office in Roydon by arrangement; call 0333 011 5550. Or book a free Google Meet video call online, or get in touch from our contact page.
Elsewhere in the borough and nearby
Hoddesdon
Immediately to the north.
Cheshunt
To the south, where the borough council is based.
Roydon
Across the River Lea, where our office is.
Hertfordshire
All the Hertfordshire towns we serve.
Areas we cover
Our full list of areas.
Bring your pensions into focus
A free first conversation with Laurence about what you have and where you want to be. No obligation.
Book a free first conversationImportant — the risks
The performance of your investments is subject to risk. Its performance may fluctuate based on movements in the market and economic conditions. Capital is at risk. Currency movements may also affect the value of investments. You may get back less than you originally invested. Past performance is not a reliable indicator of future performance. Tax treatment is based on an individual’s unique circumstances and may be subject to change.
A pension is a long-term investment — the fund value may fluctuate and can go down, and your eventual income may depend on the size of the fund at retirement, future interest rates and tax legislation.
Think carefully before securing debts against your home. Your home may be repossessed if you do not keep up repayments on your mortgage or any other debt secured on it. Please note that some mortgages, such as commercial buy-to-lets, are not regulated by the FCA.
Frequently asked questions
Should I combine my pensions?
Not always. Consolidating can make things simpler, but some pensions have guarantees or exit charges that make moving them a poor idea. We review each one before recommending anything.
What is an offset mortgage?
A mortgage linked to your savings, so that the savings balance is offset against the mortgage and you pay interest on the difference. It suits some people better than others. Your home may be repossessed if you do not keep up repayments on your mortgage.
Do you cover the whole Borough of Broxbourne?
Yes, including Broxbourne, Hoddesdon, Cheshunt and Waltham Cross.
Should I save into a pension or an ISA?
It depends on your income, goals and when you will need the money. Many people use both. We look at your circumstances before recommending anything.
Is the first meeting free?
Yes. Your first conversation is free and with no obligation.
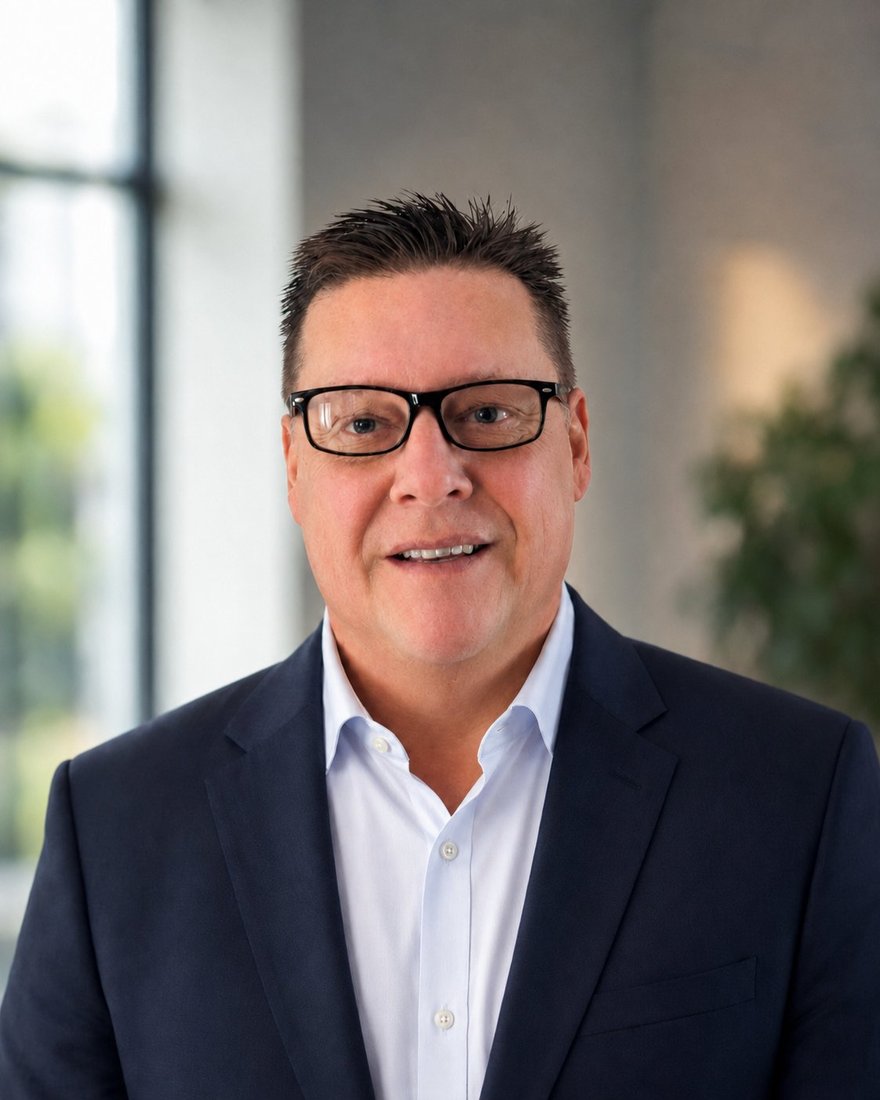
Laurence leads on pensions, investments and business protection. More about Laurence.
Important: This page is general information about the areas we serve and the services we offer. It is not personal financial advice. For advice on your specific circumstances, please get in touch.