Waltham Abbey is a historic Essex town with a strong small-business community and easy access to the M25. We are based up the Lee Valley in Roydon and help Waltham Abbey clients with everything from protecting the family business to planning a comfortable retirement.
About Waltham Abbey
The town takes its name from its medieval abbey, whose church still stands at the heart of the old town, and it sits in the Epping Forest district of Essex. The Lee Valley Regional Park runs along its western side and the former Royal Gunpowder Mills site lies on the edge of the town. Junction 26 of the M25 is close by, which is useful for businesses that rely on good road links. The town does not have its own railway station; most people use Waltham Cross, just over the county boundary in Hertfordshire.
If you run a business
Owner-managed businesses often depend heavily on one or two people. If a director, partner or key employee died or became seriously ill, the business could face lost profits, nervous lenders and difficult questions about who owns what. Business protection is designed for exactly that:
- Shareholder protection helps remaining shareholders buy the shares of a shareholder who dies or is critically ill. See our shareholder protection guide.
- Partnership protection does the same for partnerships. Read the partnership protection guide.
- Key person cover protects the business against losing someone vital to its profits.
- Relevant life plans provide death-in-service cover for directors and employees through the company.
Our business protection page covers all four. Laurence Gould leads on this area of our work.
If you let out property
Some Waltham Abbey clients own one or two rental properties alongside their home. Kealy Ball can advise on mortgages for landlords, including remortgaging a let property when a deal ends. Our buy-to-let mortgages guide explains the basics. Some buy-to-let mortgages, such as commercial buy-to-lets, are not regulated by the FCA.
If you are thinking about the future
For individuals and families, the core of what we do is long-term planning: making sure your pensions are on track, putting spare savings to work through investments that suit your attitude to risk, and having the right protection in place for the people who depend on you. If you are self-employed, it is worth thinking about this early, because there is no employer pension or sick pay to fall back on.
Retirement when you work for yourself
Employees are automatically enrolled into a workplace pension, with their employer adding money too. The self-employed get no such nudge, and it is easy for retirement saving to slip down the list when there is a business to run. Some practical points we often discuss:
- A personal pension can usually receive tax relief on contributions, within annual limits.
- If you trade through a limited company, the company may be able to contribute to your pension directly.
- Contributions can often be flexible, so you can pay more in good years and less in leaner ones.
- Relying on selling the business to fund retirement carries risk, because its value is not guaranteed.
Tax treatment depends on your individual circumstances and may change. Our retirement planning guide explains why starting early matters.
A family protection checklist
If you have a mortgage or children, it is worth asking: how much would your family need if your income stopped, for how long, and what do you already have? Death-in-service through an employer, savings and existing policies all count. The gap between what you have and what you need is what protection is there to fill.
How to reach us
Booking online sets up a free Google Meet video call. If you would prefer to talk by phone or meet at our office in Roydon, call 0333 011 5550 or send a message through the contact page.
Neighbouring areas
Cheshunt
Across the Lee Valley in Hertfordshire.
Epping
To the east, past Epping Forest.
Nazeing
North, up the Lee Valley towards Roydon.
Essex
All the Essex towns we cover.
Areas we cover
Every town and village we serve.
Protect what you have built
Whether it is your business, your property or your family’s future, a free first conversation is the place to start.
Book a free first conversationImportant — the risks
The performance of your investments is subject to risk. Its performance may fluctuate based on movements in the market and economic conditions. Capital is at risk. Currency movements may also affect the value of investments. You may get back less than you originally invested. Past performance is not a reliable indicator of future performance. Tax treatment is based on an individual’s unique circumstances and may be subject to change.
A pension is a long-term investment — the fund value may fluctuate and can go down, and your eventual income may depend on the size of the fund at retirement, future interest rates and tax legislation.
Think carefully before securing debts against your home. Your home may be repossessed if you do not keep up repayments on your mortgage or any other debt secured on it. Please note that some mortgages, such as commercial buy-to-lets, are not regulated by the FCA.
Frequently asked questions
Do you work with small businesses in Waltham Abbey?
Yes. We advise company directors, partners and sole traders on business protection, relevant life plans and pensions.
Can you help with a buy-to-let mortgage?
Yes. Kealy Ball can help landlords with buy-to-let purchases and remortgages. Some buy-to-let mortgages are not regulated by the FCA. Your home may be repossessed if you do not keep up repayments on your mortgage.
How far are you from Waltham Abbey?
Our office is in Roydon, a few miles north up the Lee Valley. Many clients choose a video call or phone call instead of travelling.
I’m a sole trader. Do I need a pension?
There is no legal requirement, but without an employer scheme it is up to you to save for retirement. A personal pension is one option, and contributions can usually receive tax relief within annual limits, depending on your circumstances.
Is the first meeting free?
Yes. Your first conversation is free and without obligation.
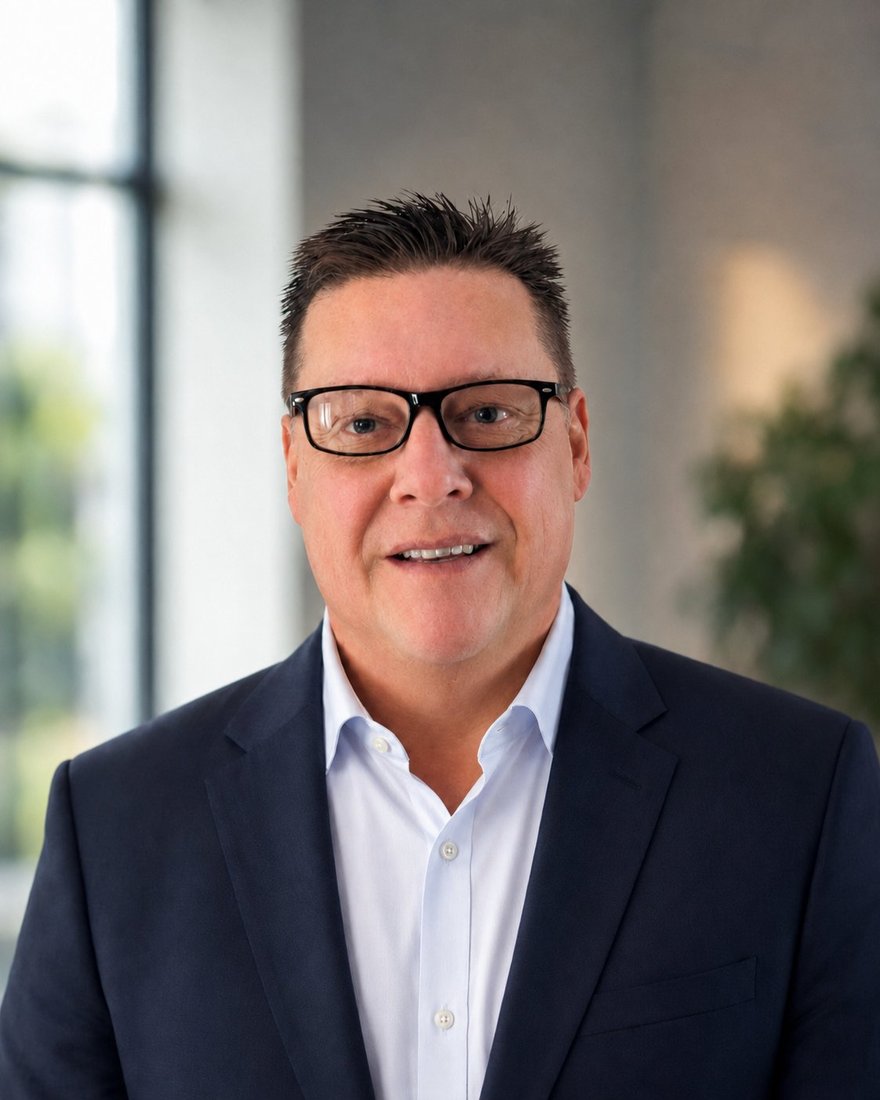
Laurence leads on pensions, investments and business protection. More about Laurence.
Important: This page is general information about the areas we serve and the services we offer. It is not personal financial advice. For advice on your specific circumstances, please get in touch.