Harlow is our nearest town. Lynfield sits on Harlow Road in Roydon, just west of Harlow, and our office shares the town’s CM19 postcode. Whether you live in Old Harlow, the new town neighbourhoods or one of the newer developments on the edge of town, we are close by and happy to help.
Old town, new town
Harlow is really two places. Old Harlow is the original settlement, with its own High Street and a history that goes back long before the twentieth century. The town most people know today was designated as one of Britain’s post-war new towns in 1947 and planned by the architect Sir Frederick Gibberd, built around neighbourhoods such as The Stow, Bush Fair and Staple Tye, and later Church Langley and Newhall.
That mix shows up in the money questions people bring to us. Long-standing Old Harlow residents are often thinking about retirement income and what they will pass on. Younger households in the newer neighbourhoods are more likely to be buying, remortgaging or trying to work out how much life cover they need. Harlow is administered by Harlow Council, sits in Essex, and is well connected: Harlow Town and Harlow Mill stations are on the West Anglia Main Line into London Liverpool Street, and the M11 runs along the town’s eastern edge.
Beyond the town itself, we look after clients in the villages to the east and north-east of Harlow, including Sheering, Matching Green and Matching Tye, which sit in the Epping Forest district.
Money questions we hear from Harlow households
“I’ve got pensions from three different jobs”
Harlow has a large working population spread across its business areas, so it is common to have small workplace pensions from several employers. We can trace and review them and talk through whether bringing them together makes sense. Consolidating isn’t right for everyone, so we look at charges, guarantees and your own plans before recommending anything. See our pensions and retirement page and our guide to automatic enrolment for employees.
“We want to buy our first home”
Kealy Ball, our mortgage and protection specialist, lives in Harlow herself. She helps first-time buyers from decision in principle through to completion, and can look at remortgages, moving home and buy-to-let too. Read our first-time buyers guide or visit the mortgages page.
“If something happened to me, would the family be all right?”
Protection is often the gap in a household’s plans. Life cover, critical illness cover and income protection can be arranged to match your mortgage and family commitments. Our protection page explains the main options.
“I run a business in Harlow”
For company directors and partners, we advise on business protection, including key person cover and shareholder protection, and on workplace pension duties. Our key person insurance guide is a good starting point.
“I want my savings to work harder”
If you have cash building up, we can talk about investments that match your goals and your attitude to risk. Investing is not right for money you may need soon, and the value of investments can fall as well as rise.
When is a good time to speak to an adviser?
There is no wrong time, but certain moments tend to prompt a conversation. If any of these apply to you, it may be worth getting in touch:
- You have started a new job and need to decide what to do with your old workplace pension.
- You are expecting a baby, or your children have just started school, and you want to know your family would be looked after.
- Your fixed-rate mortgage ends in the next six months or so.
- You have received an inheritance, a redundancy payment or a bonus and are not sure what to do with it.
- You are within ten years of the age you would like to retire.
- You are thinking of selling, passing on or bringing a partner into your business.
In each case, the first conversation is about understanding where you are. We will only suggest a course of action once we know your circumstances, and we will explain the risks as well as the benefits. Sometimes the right advice is to leave things as they are.
Renting now, buying later
Plenty of Harlow residents are renting while they save for a deposit. A conversation with Kealy early on can help you understand what lenders are likely to look for, how much you might be able to borrow and how long it may take to get there. That makes it easier to set a realistic savings target, and avoids surprises when you find the right home.
How meeting us works
Booking online sets up a free Google Meet video call, which many Harlow clients find easiest around work and school runs. If you would rather speak by phone, or meet face to face at our office in Roydon, call us on 0333 011 5550 and we will arrange a time that suits. You can also send us a message through our contact page.
Near Harlow
Roydon
Our home village, just west of Harlow along the Stort valley.
Sawbridgeworth
The next town north, between Harlow and Bishop’s Stortford.
Epping
South of Harlow, at the end of the Central line.
All of Essex
Our Essex page, covering every Essex town we serve.
Areas we cover
The full list of towns and villages across Hertfordshire and Essex.
Talk to a Harlow-area adviser
A first conversation is free and there is no obligation. Choose Laurence for pensions, investments and business protection, or Kealy for mortgages and protection.
Book a free first conversationImportant — the risks
The performance of your investments is subject to risk. Its performance may fluctuate based on movements in the market and economic conditions. Capital is at risk. Currency movements may also affect the value of investments. You may get back less than you originally invested. Past performance is not a reliable indicator of future performance. Tax treatment is based on an individual’s unique circumstances and may be subject to change.
A pension is a long-term investment — the fund value may fluctuate and can go down, and your eventual income may depend on the size of the fund at retirement, future interest rates and tax legislation.
Think carefully before securing debts against your home. Your home may be repossessed if you do not keep up repayments on your mortgage or any other debt secured on it. Please note that some mortgages, such as commercial buy-to-lets, are not regulated by the FCA.
Frequently asked questions
Is your office in Harlow?
We are at Lynfield, Harlow Road, Roydon, Harlow CM19 5HH, just outside Harlow on the Roydon side. It is a short drive from Harlow town centre and Old Harlow.
Do you cover Old Harlow as well as the rest of the town?
Yes. We help clients in Old Harlow, Church Langley, Newhall and every other part of Harlow, as well as the surrounding villages.
Can you help me combine old workplace pensions?
Yes, we can review whether bringing your pensions together is right for you. Consolidating isn’t right for everyone, so we look at your individual circumstances first.
Can you arrange a mortgage for a Harlow property?
Yes. Kealy Ball is our mortgage broker and can help with buying, moving and remortgaging. Your home may be repossessed if you do not keep up repayments on your mortgage.
I’m renting. Is it too early to talk about a mortgage?
No. Talking early can help you understand what lenders look for and how much you might be able to borrow, so you can plan your deposit savings. Your home may be repossessed if you do not keep up repayments on your mortgage.
Is the first meeting free?
Yes. Your first conversation is free and with no obligation, by video call, phone or in person at our Roydon office.
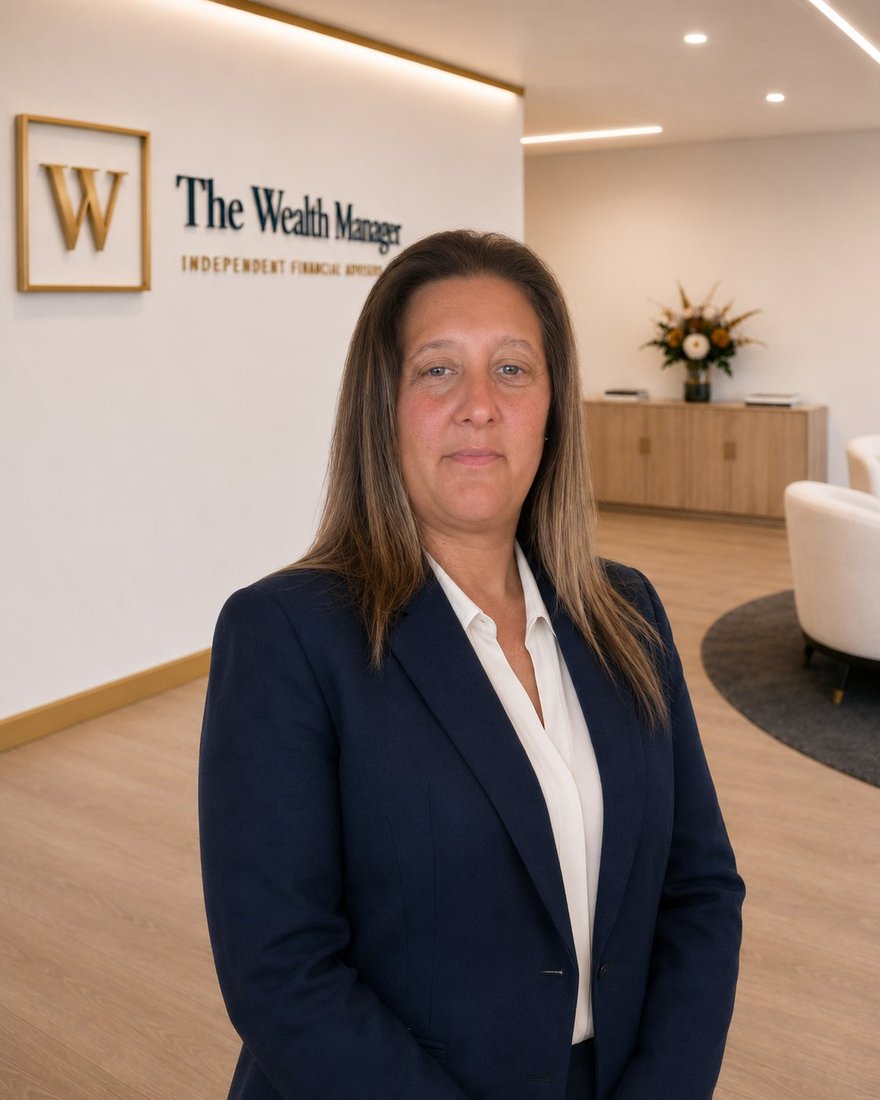
Kealy is our mortgage and protection specialist. More about Kealy.
Important: This page is general information about the areas we serve and the services we offer. It is not personal financial advice. For advice on your specific circumstances, please get in touch.