Sawbridgeworth is a small, characterful town on the River Stort, between Harlow and Bishop’s Stortford. A good number of the conversations we have with people there are about retirement: when to stop work, how to turn savings into an income, and how to make it last. This page focuses on that, while covering the rest of what we do too.
About the town
Sawbridgeworth lies in East Hertfordshire on the west bank of the Stort, which forms the county boundary with Essex here. Its station, on the West Anglia Main Line, has trains to London Liverpool Street and to Bishop’s Stortford and Cambridge. Harlow is immediately to the south, and our Roydon office is a short drive beyond it.
We also help people in High Wych, the neighbouring village to the south-west, whose parish also takes in Allen’s Green and Trimm’s Green.
Planning the move into retirement
Working out what you have
The first step is a clear list: workplace pensions, personal pensions, any defined benefit entitlement, your State Pension forecast, ISAs and other savings. Many people are surprised by what they find, in both directions.
Deciding how to take an income
Broadly, you can buy an annuity, which provides a secure income for life, or keep your pension invested and draw from it flexibly, known as drawdown. Some people use a mix of both. Drawdown offers more flexibility, but your income is not guaranteed and the fund can fall in value. Our income drawdown guide sets out the pros and cons.
Thinking about tax
How and when you draw on pensions and other savings can affect how much tax you pay. Tax treatment depends on your individual circumstances and may change in the future, so we look at your own position.
Making it last
People are generally living longer than they expect. A plan should allow for a long retirement and be reviewed as life changes. Our guide to the value of retirement planning explains why.
Thinking about the family
Many retirees want to help children or grandchildren, or leave something behind. Life cover written in the right way, such as whole of life assurance, is one tool that can be used as part of those plans.
Our pensions and retirement page has more on how we help.
Not retiring just yet?
We also help Sawbridgeworth residents who are much earlier on, with:
- Investments chosen around your goals and attitude to risk.
- Protection for you and your family.
- Mortgages for buying, moving and remortgaging, arranged by Kealy Ball.
- Business protection for owners and directors.
Common retirement pitfalls
Some of the most common mistakes are also the easiest to avoid:
- Forgetting old pensions. A pension from a job decades ago can still be worth claiming.
- Not checking the State Pension. Gaps in your National Insurance record can reduce it; a forecast from GOV.UK shows where you stand.
- Taking tax-free cash without a plan. Taking a lump sum can be the right move, but it is worth knowing what it is for and how it affects the rest of your pension.
- Overlooking inflation. An income that feels comfortable today will buy less in twenty years.
- Leaving beneficiary details out of date. Check who you have nominated to receive your pensions and life cover.
- Drawing too much too soon. With drawdown, taking large withdrawals early, especially when markets have fallen, can shorten how long your fund lasts.
None of these needs complicated solutions, just a clear look at the facts and a plan that is reviewed as you go.
Meeting us
Retirement conversations can be detailed, and some people prefer to sit down face to face. We are happy to meet at our Roydon office; call 0333 011 5550 to arrange it. You can also book a free Google Meet video call online or reach us through the contact page.
Neighbouring towns
Bishop’s Stortford
A few miles north up the Stort.
Harlow & Old Harlow
Immediately to the south, across the river.
Roydon
Where our office is.
Hertfordshire
Every Hertfordshire town we serve.
Areas we cover
Our full list of areas.
Thinking about retirement?
Start with a free, no-obligation conversation with Laurence about where you are and where you would like to be.
Book a free first conversationImportant — the risks
The performance of your investments is subject to risk. Its performance may fluctuate based on movements in the market and economic conditions. Capital is at risk. Currency movements may also affect the value of investments. You may get back less than you originally invested. Past performance is not a reliable indicator of future performance. Tax treatment is based on an individual’s unique circumstances and may be subject to change.
A pension is a long-term investment — the fund value may fluctuate and can go down, and your eventual income may depend on the size of the fund at retirement, future interest rates and tax legislation.
Think carefully before securing debts against your home. Your home may be repossessed if you do not keep up repayments on your mortgage or any other debt secured on it. Please note that some mortgages, such as commercial buy-to-lets, are not regulated by the FCA.
Frequently asked questions
When can I access my pension?
Under current rules, most people can access personal and workplace pensions from age 55, rising to 57 from April 2028. Some schemes have different rules, so it is worth checking yours.
Should I choose drawdown or an annuity?
It depends on your need for a secure income, your other savings, your health and your attitude to risk. Many people use a combination. We talk through the options before recommending anything.
Can we meet face to face?
Yes. Call 0333 011 5550 to arrange a meeting at our office in Roydon, or book a free video call online.
How do I check my State Pension?
You can get a State Pension forecast online from GOV.UK. It shows how much you may get and whether there are gaps in your National Insurance record.
Is the first meeting free?
Yes. Your first conversation is free and with no obligation.
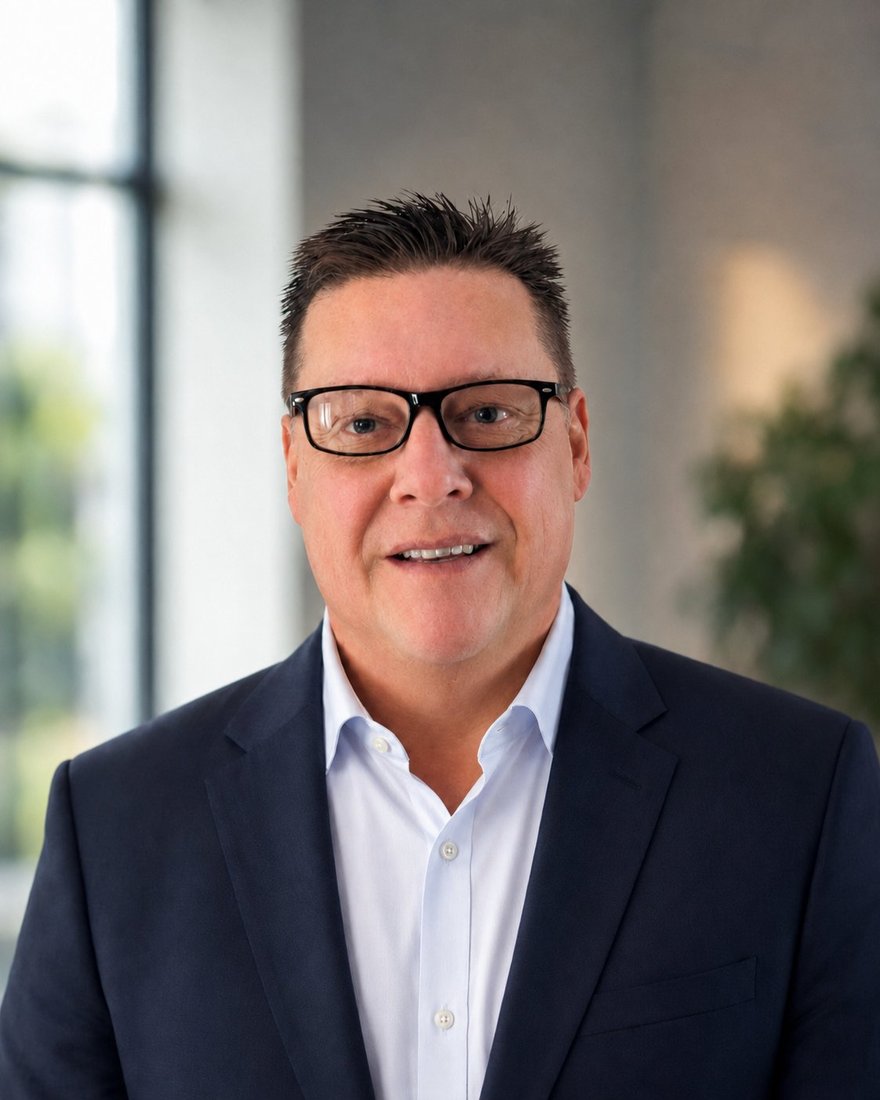
Laurence leads on pensions, investments and business protection. More about Laurence.
Important: This page is general information about the areas we serve and the services we offer. It is not personal financial advice. For advice on your specific circumstances, please get in touch.