When money feels tight or muddled, the hardest part is knowing what to do first. Should you overpay the mortgage, start investing, or sort out life cover? This page sets out a simple order of priorities that works for many households in Waltham Cross, and explains where we can help along the way.
About Waltham Cross
Waltham Cross is a town in the Borough of Broxbourne, in the far south-east corner of Hertfordshire. It takes its name from the Eleanor Cross in the town centre, one of the memorials Edward I put up after the death of Queen Eleanor in 1290, and one of only three of the originals still standing. Waltham Cross station is on the West Anglia Main Line, Theobalds Grove station is on London Overground’s Weaver line, and junction 25 of the M25 is on the edge of town. Waltham Abbey is just across the River Lea in Essex.
Our office is in Roydon, a short drive up the Lee Valley. You can meet us there, or book a free Google Meet video call online.
A rough order of priorities
Everyone’s situation is different, and this is not personal advice. But as a starting point, this order makes sense for a lot of people.
- Know your numbers. Write down what comes in and what goes out each month. It is hard to plan anything without this.
- Deal with expensive debt. Credit cards and other high-interest borrowing usually cost more than savings can earn.
- Build an emergency fund. A cash buffer for unexpected bills stops a broken boiler becoming a new debt.
- Protect your income and your family. If others depend on you, consider what would happen if you could not work or were no longer here.
- Take the free money. If your employer will put more into your pension when you do, that is often hard to beat.
- Get the mortgage right. Make sure you are not drifting onto a higher rate when a fixed deal ends.
- Invest for the longer term. Once the foundations are in place, money you will not need for some years can be invested.
Step 4 in more detail: protection
Protection is the step people most often skip, usually because it feels expensive or complicated. It does not have to be either. Level term assurance pays a fixed sum if you die within the term. Decreasing term assurance is often used alongside a repayment mortgage, because the cover reduces as the debt does. Income protection pays a monthly amount if illness or injury stops you working. Kealy can look at what you already have through work before suggesting anything new. See our protection page.
Step 5 in more detail: your workplace pension
Most employees are now enrolled in a workplace pension automatically. It is worth checking how much is going in, whether your employer would match more, and how the money is invested. Our guide to automatic enrolment for employees explains the basics, and Laurence can help if you have several old pensions to make sense of. See pensions.
Step 6 in more detail: the mortgage
When a fixed or tracker deal ends, many mortgages move onto the lender’s standard variable rate, which may be higher. Speaking to a broker a few months beforehand gives you time to compare options. Kealy can help with remortgaging, moving home or a first purchase. See our mortgages page.
Step 7 in more detail: investing
Investing means accepting that values will go up and down, so it suits money you can leave alone for at least five years. Our investment overview explains the main options, and our investments page explains how we approach risk.
Neighbouring areas
Cheshunt
Next door, also in the Borough of Broxbourne.
Waltham Abbey
Just across the River Lea in Essex.
Enfield
South, over the M25.
Hertfordshire
All the Hertfordshire towns we serve.
Not sure where to start?
Tell us where you are in a free first conversation, and we will help you work out the next step. There is no obligation.
Book a free first conversationImportant — the risks
The performance of your investments is subject to risk. Its performance may fluctuate based on movements in the market and economic conditions. Capital is at risk. Currency movements may also affect the value of investments. You may get back less than you originally invested. Past performance is not a reliable indicator of future performance. Tax treatment is based on an individual’s unique circumstances and may be subject to change.
A pension is a long-term investment — the fund value may fluctuate and can go down, and your eventual income may depend on the size of the fund at retirement, future interest rates and tax legislation.
Think carefully before securing debts against your home. Your home may be repossessed if you do not keep up repayments on your mortgage or any other debt secured on it. Please note that some mortgages, such as commercial buy-to-lets, are not regulated by the FCA.
Frequently asked questions
Should I pay off debt or save first?
It depends on your situation, but expensive debt such as credit cards usually costs more than savings earn. Many people tackle that first while building a small emergency fund.
Is protection worth it if I am young and healthy?
If anyone depends on your income, it is worth considering. Cover is often more affordable when you are younger, and we check what you already have through work first.
When should I look at my remortgage?
A few months before your current deal ends is usually a good time, so there is time to compare options. Your home may be repossessed if you do not keep up repayments on your mortgage.
How far is your office from Waltham Cross?
Our office in Roydon is a short drive up the Lee Valley. You can also meet us by video call or phone.
Is the first meeting free?
Yes. Your first conversation is free and with no obligation.
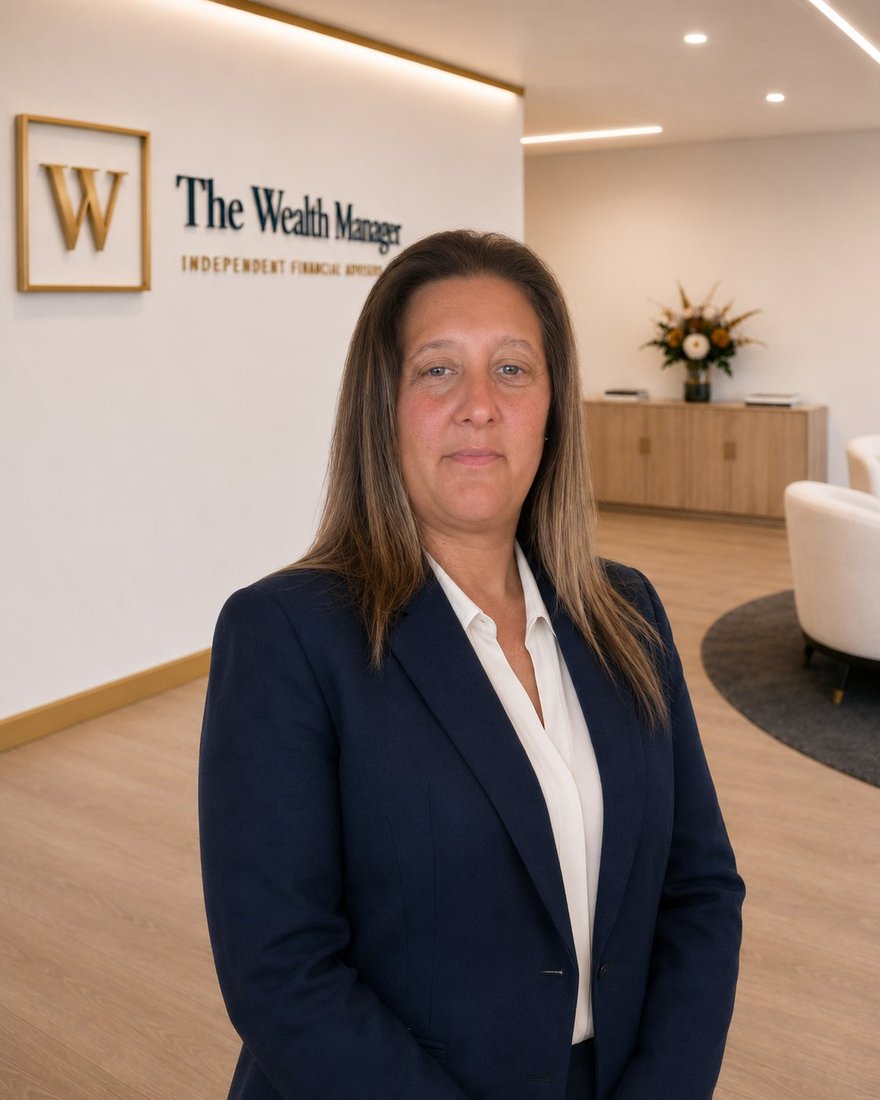
Kealy is our mortgage and protection specialist. More about Kealy.
Important: This page is general information about the areas we serve and the services we offer. It is not personal financial advice. For advice on your specific circumstances, please get in touch.